
Waking Up to a Legal Nightmare: My Personal Wake-Up Call
You just survived a car crash, and now your phone won't stop ringing. On the other end? An insurance adjuster acting like your best friend, ready to offer you a quick check. I know how tempting it is to just take the money and move on, but wait! Before you sign anything, you need to know that their first offer is almost always a trap. Today, I am going to show you exactly how to fight back and get the real payout you deserve. Let's get straight to it.
I honestly thought my insurance company would just step in, pay the medical bills, and make things right. I was completely wrong. Instead, I found myself trapped in a nightmare of endless phone calls, aggressive adjusters, and confusing paperwork.
Every time the phone rang, my stomach would tie itself into knots. I quickly realized that the people on the other end of the line were not my friends. They were highly trained professionals whose only job was to save their company money, even if it meant leaving me in debt.
If you are reading this right now, you are probably feeling that exact same heavy weight on your chest. You did not ask for this crash to happen. You simply want to fix your car, heal your body, and get your life back to normal.
The stress of the physical pain is hard enough to handle on its own. But when you add the mental exhaustion of fighting a massive corporation, it can completely destroy your peace of mind. Regular people are losing sleep, missing work, and draining their savings just trying to prove they deserve help.
What You Will Learn Today:
- Why you should always treat the very first settlement offer as a joke.
- How keeping a simple daily "pain journal" can double your payout money.
- The exact words you need to say (and what to avoid) when talking to an adjuster.
- When it actually makes sense to call a lawyer for extra help.
The endless back-and-forth communication makes you second-guess your own memory. You might even feel like giving up just to make the headache stop. But walking away is the biggest error you can make, and understanding your rights is your strongest shield against their tactics.
Navigating the Maze: A Proven Blueprint to Protect Your Rights
Filing an insurance settlement is a highly strategic game. If you do not know the rules, you will automatically lose. To protect your financial future, you must understand exactly how the system works from the inside out. Let's break down the most essential strategies you need to apply right now.
Before you say a single word to an insurance adjuster, watch this short breakdown of how they secretly use your own words against you.
The Immediate Aftermath: Capturing the Right Evidence
The moments immediately following a crash are chaotic and terrifying. However, the evidence you gather during these first few hours will absolutely make or break your entire case. Memory fades rapidly, and physical evidence disappears even faster.
You must act like a private investigator at the scene. The insurance company will base their initial evaluation purely on the hard evidence presented to them. Without solid proof, it simply becomes your word against the other driver's word.
Why Photographs Are Your Best Witness
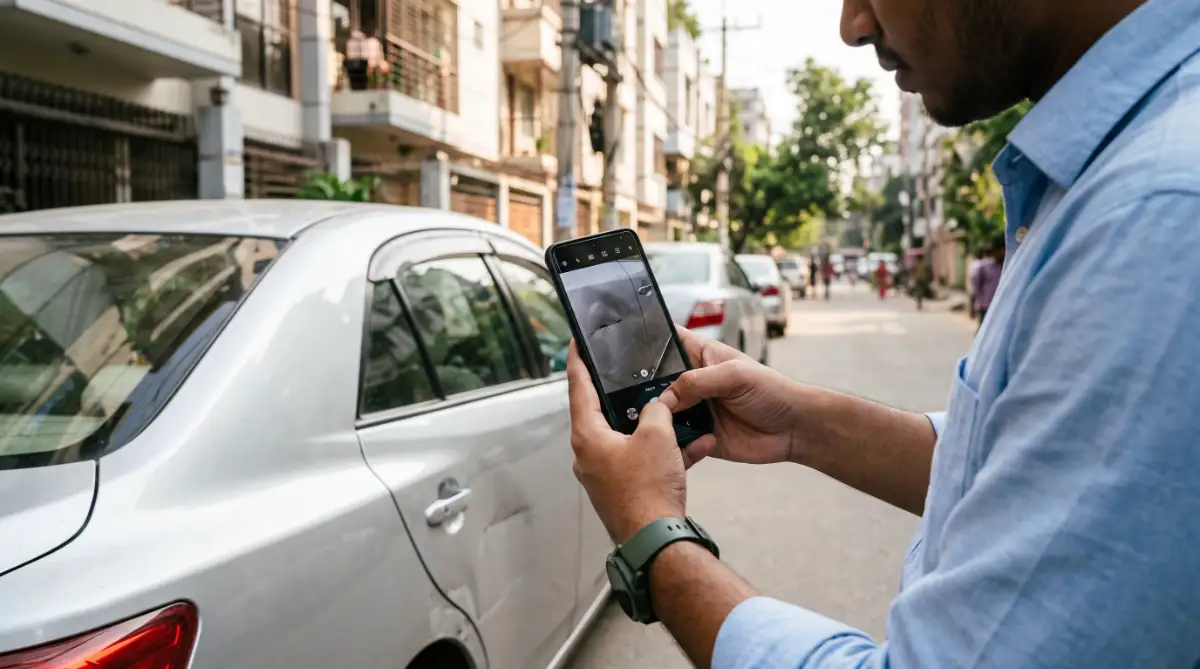
Most people just take a quick picture of their damaged bumper and call it a day. This is a massive missed opportunity. You need to capture the entire environment to tell the full story of what happened.
Take wide shots of the intersection, the weather conditions, and any skid marks on the road. Photograph the license plates, the positioning of the vehicles, and even any visible injuries you have sustained. The more angles you capture, the harder it is for the other side to twist the truth.
Evidence Comparison Chart:
Managing the Medical Paper Trail
Your physical health should always be your top priority. But in the eyes of an insurance corporation, your injuries only exist if they are perfectly documented on paper. A gap in your medical records is the easiest way for an adjuster to deny your entire file.
When you seek medical attention, you are creating a timeline. This timeline proves exactly when the injury happened and how severe it is. Skipping doctor appointments or ignoring therapy sessions sends a clear message that you are not actually hurt.
The Hidden Danger of Delayed Treatment
Adrenaline is a powerful chemical that masks physical pain after a traumatic event. You might walk away from a crash feeling totally fine, only to wake up three days later unable to move your neck.
If you wait two weeks to see a doctor, the insurance company will argue that your injury happened somewhere else. They will claim you hurt your back while lifting a heavy box at home, not during the crash. You must establish a medical baseline within 24 to 48 hours.
I made the huge mistake of trying to push through the pain because I didn't want to miss work. My delay in seeing a doctor gave the insurance company the exact excuse they needed to claim my injuries were not from the crash at all. Please, do not try to be a hero; get checked out immediately, even if you feel okay.
Dealing With Adjusters: What They Don't Tell You
Insurance adjusters are trained negotiators. Their friendly tone on the phone is a calculated technique designed to make you drop your guard. They want you to trust them so you will say things that accidentally ruin your case.
They often call you when you are still in shock or heavily medicated. During this vulnerable time, they will ask you to provide an official statement. This is a massive trap that you must avoid at all costs.
The Recorded Statement Trap
When an adjuster asks for a recorded statement, they are not trying to learn the truth. They are fishing for inconsistencies in your story. A simple answer like "I'm doing okay today" can be twisted to mean you are no longer injured.
You are legally obligated to cooperate with your own insurance company. However, you are never required to give a recorded statement to the at-fault driver’s company without legal representation. Politely decline and tell them you will submit all necessary information in writing.
Myth vs. Reality: Dealing with the Insurance Company
The First Offer Trap
- The Myth: The insurance adjuster gives you their best offer right away to save you time.
- The Fact: That first check is basically a test. They want to see if you are desperate enough to take pennies. I always tell my friends to treat the first offer as the starting line, not the finish line. Never accept it on day one.
- The Myth: The first settlement offer is usually fair and saves time.
- The Reality: The initial offer is almost always a lowball figure designed to see how desperate you are. It rarely covers future medical expenses or long-term suffering.
- The Myth: Signing a blanket medical authorization form is required to process the paperwork.
- The Reality: Signing a blank authorization gives them access to your entire medical history from birth. They will search for prior conditions to blame your current pain on. Never sign a blank release form.
Decoding the Fine Print of Your Policy
Most people have no idea what their actual coverage limits are until a disaster strikes. Reading an insurance policy can feel like reading a foreign language. But understanding your specific coverages is the only way to maximize your recovery.
Your declaration page outlines the exact dollar amounts available to you. You need to identify your liability limits, collision coverage, and medical payment options. This pool of money is what you will be negotiating for.
Uninsured and Underinsured Coverage Explained
One of the worst scenarios is getting hit by someone who has no insurance at all. Sadly, this happens every single day. If you do not have Uninsured Motorist (UM) coverage, you might be left paying for everything out of your own pocket.
Always review your own policy before making any demands. Sometimes, your own company is the one that will actually compensate you for your losses.
Calculating the True Cost of Your Damage
Assigning a dollar value to your suffering is incredibly complex. The insurance company uses sophisticated software programs to generate a settlement number. These programs are programmed to minimize payouts by ignoring the human element of your trauma.
You cannot rely on their math to determine your future needs. You must build your own comprehensive list of damages. This list needs to include every single penny this incident has cost you, both right now and in the future.
Beyond the Car: Pain, Suffering, and Lost Wages
Property damage is easy to calculate because a mechanic can just print an estimate. Bodily injury is entirely different. How do you put a price tag on not being able to pick up your child because your back is destroyed?
Special damages refer to your exact out-of-pocket expenses. This includes ambulance rides, emergency room visits, physical therapy, and the wages you lost while recovering at home. You need receipts, pay stubs, and invoices to prove every single item on this list.
General damages cover your pain, emotional distress, and loss of enjoyment in life. Because there are no receipts for sadness or anxiety, you must keep a daily journal. Documenting your daily struggles gives concrete evidence of how the crash has altered your daily routine. A well-kept recovery journal forces the adjuster to see you as a human being, not just a file number.
Next-Level Tactics: Insider Strategies for Maximum Compensation
Winning an insurance negotiation is not about getting lucky. It is about outsmarting a system that was specifically built to wear you down and make you quit. Once you master the basic rules of evidence and medical records, you need to understand the hidden psychology of the people handling your file.
The most successful claims are built by people who treat the process like a serious business transaction. You have to remove your emotions from the equation completely. This is incredibly hard when you are in physical pain, but it is the only way to get the money you deserve.
Understanding the Adjuster's Secret "Reserve"
When your case is first opened, the insurance company immediately assigns a specific dollar amount to it. This amount is called the "reserve," and it represents the maximum amount of money they expect to pay you. The adjuster’s primary goal is to settle your case for significantly less than that reserve amount.
If they can close your file for half of the reserve, they look like a superstar to their boss. They will use every psychological trick in the book to make you think your case is worthless. You have to remember that their initial evaluation is just an educated guess based on very little information.
You have the power to force them to increase that reserve limit. You do this by consistently sending them overwhelming proof of your injuries and financial losses. When you provide rock-solid documentation, they have no choice but to adjust their internal numbers to reflect the reality of your situation.
The Power of Extreme Patience
The insurance company knows that regular people have bills to pay. They know you are likely missing work and feeling the heavy squeeze of a shrinking bank account. They will intentionally drag out the process, hoping your financial desperation will force you to accept a terrible offer.
This is exactly why building an emergency fund fast is one of the smartest things you can do before disaster strikes. Having a financial cushion allows you to say "no" to their lowball offers without panicking. It gives you the breathing room to wait for a fair resolution.
If you are currently living paycheck to paycheck, you are in a highly vulnerable position. Relying entirely on one income source makes the waiting game feel impossible. However, giving in to their delay tactics will cost you thousands of dollars in the long run.
According to resources from the American Bar Association regarding personal injury claims, understanding your legal standing gives you the leverage to negotiate fairly. You must hold your ground and let the legal process work its course. Patience is not just a virtue here; it is your most profitable weapon.
Crafting a Bulletproof Demand Letter
Eventually, you will reach a point where your medical treatment is finished, or your doctor says you will not recover any further. This is called Maximum Medical Improvement (MMI). This is the exact moment you strike by sending a formal demand letter.
A demand letter is a carefully written document that summarizes your entire ordeal. It outlines the facts of the crash, details every single medical procedure, and explains how your daily life was ruined. Most importantly, it ends with a specific financial demand for your settlement.
Do not just throw a random number on a piece of paper. You must justify every single dollar you are asking for with receipts, invoices, and a logical explanation of your pain. A weak demand letter will be tossed in the trash, but a highly detailed one forces the adjuster to take you seriously.
The Silent Traps That Destroy Honest Accident Settlements
Even if you have the perfect evidence and a brilliant demand letter, you can still lose everything by making one foolish mistake. The insurance company is actively watching you, waiting for you to slip up. They have entire teams dedicated to finding reasons to deny your coverage.
People often sabotage their own success without even realizing it. They make innocent decisions that look terrible on paper. Let’s explore the most dangerous traps you must avoid at all costs if you want to protect your financial future.
The Social Media Surveillance Trap
We live in a highly connected society where people share every detail of their lives online. If you are in the middle of a legal dispute, your social media accounts are your biggest enemy. Insurance investigators will comb through your Facebook, Instagram, and TikTok looking for anything they can use against you.
Imagine you claim you have severe back pain and cannot work. A week later, your friend tags you in a photo smiling at a weekend barbecue. The insurance company will use that single smiling photo to argue that you are completely faking your injuries.
They do not care that you were only smiling for ten seconds before going back home to lie on a heating pad. They only care about creating a narrative that ruins your credibility. The smartest move you can make is to set all your profiles to completely private and stop posting entirely until the money is in your bank account.
Signing the Early Release of Liability
A few days after your crash, the adjuster might call you sounding incredibly helpful and sweet. They might offer to pay your current medical bills and throw in an extra two thousand dollars for your trouble. All they ask in return is that you sign a simple piece of paper.
Quick Q&A: Should I give a recorded statement?
Question: The insurance company is asking to record my side of the story. Should I say yes?
My Answer: Absolutely not. You have no legal obligation to give a recorded statement to the other driver's insurance company. They often use these recordings to twist your words and lower your payout. Just tell them politely, "I am not comfortable being recorded right now," and stick to the basic facts.
That piece of paper is a release of liability. The moment you sign your name on that dotted line, your case is permanently closed forever. You can never go back and ask for another penny, even if you need massive surgery three months later.
This is a classic predatory tactic. They want to buy their way out of a massive future expense with a tiny, immediate check. You might think you are getting a great deal, but you are actually falling for secret habits that silently drain your finances by giving up your true compensation. Never sign a release until a professional confirms it is safe.
Falling for the "Independent" Medical Exam
If your treatment goes on for a long time, the insurance company might demand that you see a doctor of their choosing. They will call this an Independent Medical Examination (IME). Let me be completely clear: there is absolutely nothing independent about this doctor.
These doctors are hired and paid directly by the insurance corporation. Their primary job is to find a medical reason to cut off your benefits. They will spend five minutes examining you and then write a twenty-page report claiming you are perfectly fine.
You usually have to attend this exam if it is in your policy, but you do not have to go in blind. Bring a trusted friend or family member to sit in the room with you and take detailed notes. Record exactly how long the doctor spends with you and what questions they ask so you can challenge their biased report later.
The Danger of Predatory Lawsuit Loans
When the bills start piling up and the insurance company refuses to pay, panic sets in quickly. This desperation leads many people straight into the arms of settlement loan companies. These companies offer to give you a cash advance on your future settlement.
While getting cash today sounds amazing, the interest rates on these loans are absolutely terrifying. You could end up paying back double or triple what you borrowed. Understanding the secret psychology of borrowing money will help you see that these loans are designed to trap you in debt.
By the time your settlement finally arrives, the loan company might take almost the entire check. The Consumer Financial Protection Bureau (CFPB) heavily warns against these types of high-interest cash advances. Exhaust every other option, like borrowing from family or negotiating payment plans with your hospital, before you ever consider a lawsuit loan.